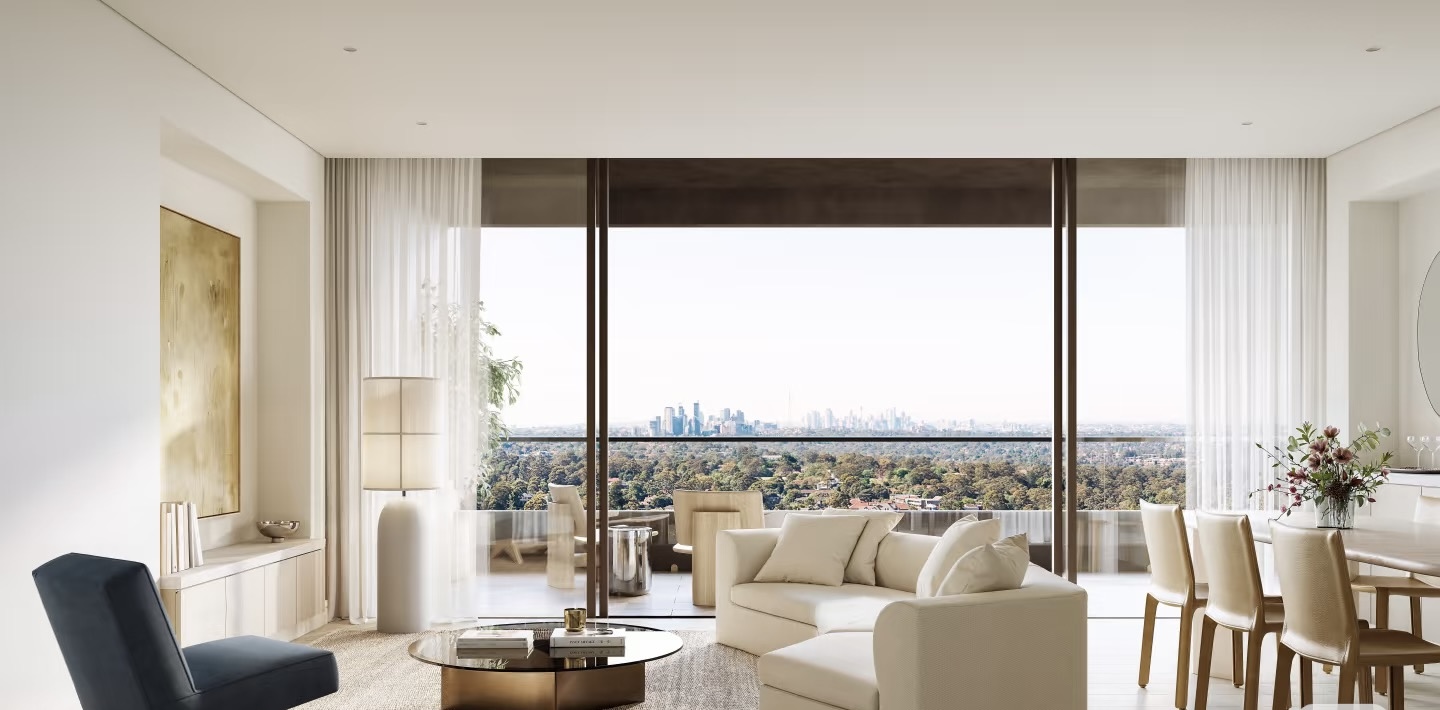
Gordon, NSW — Off-Plan
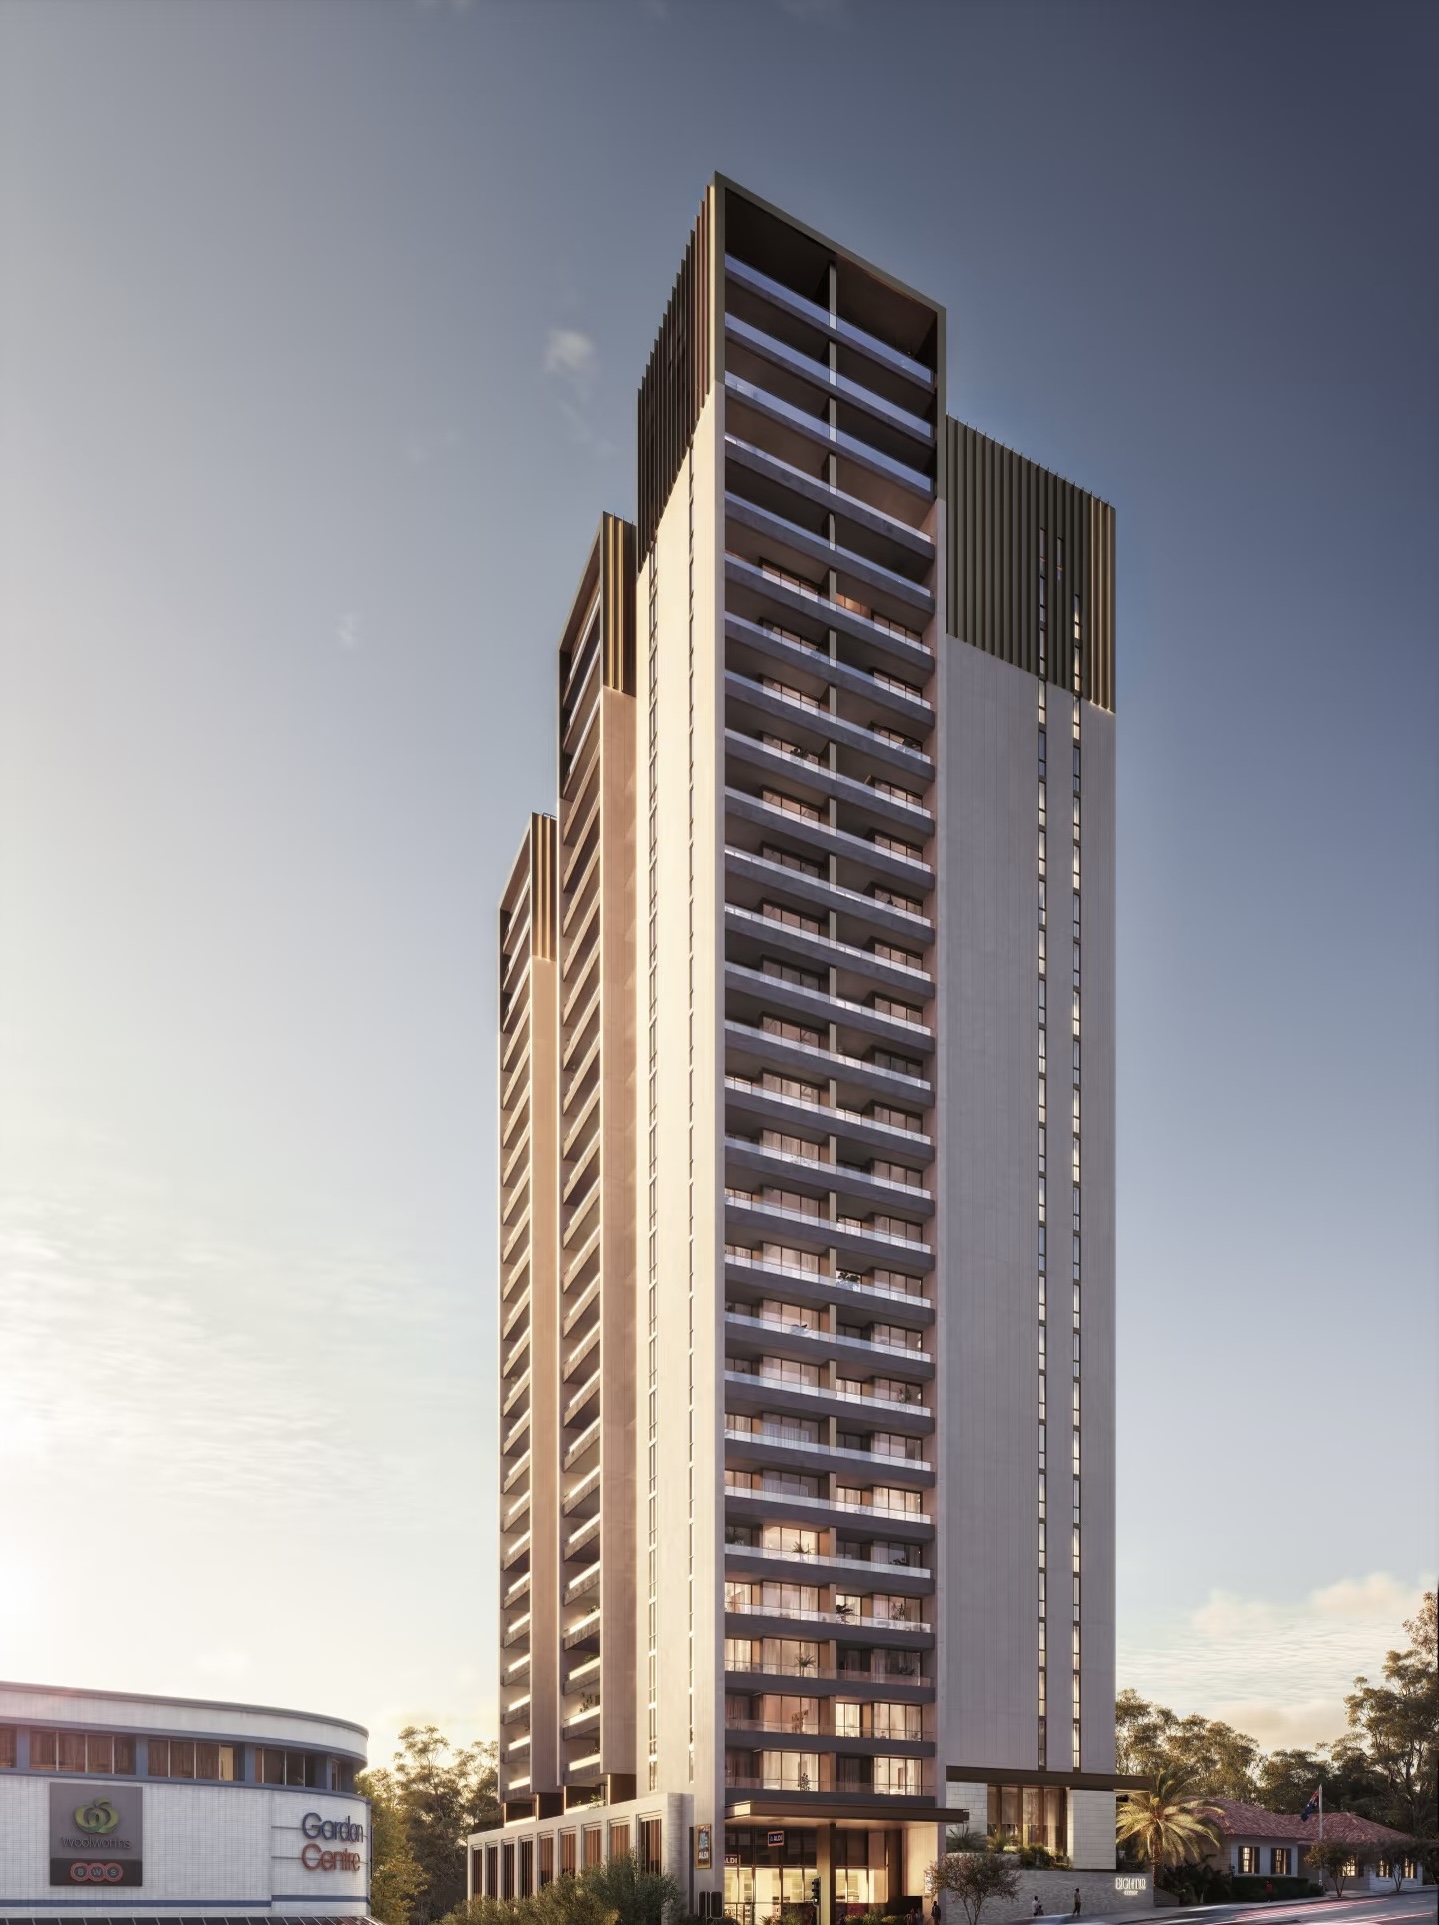
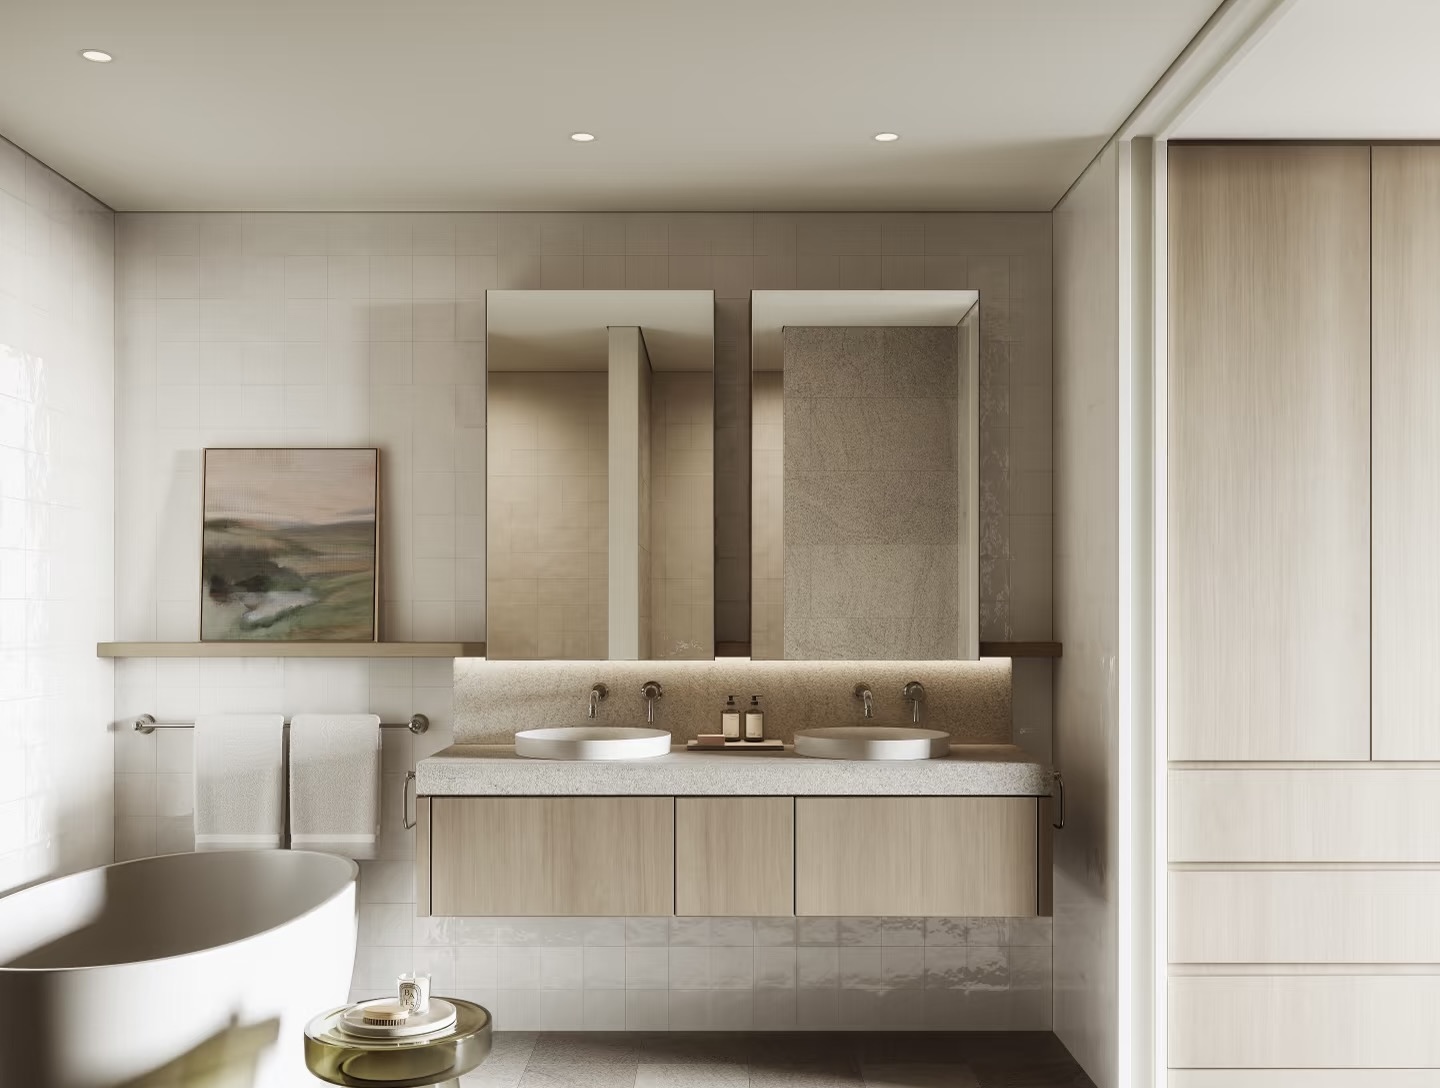
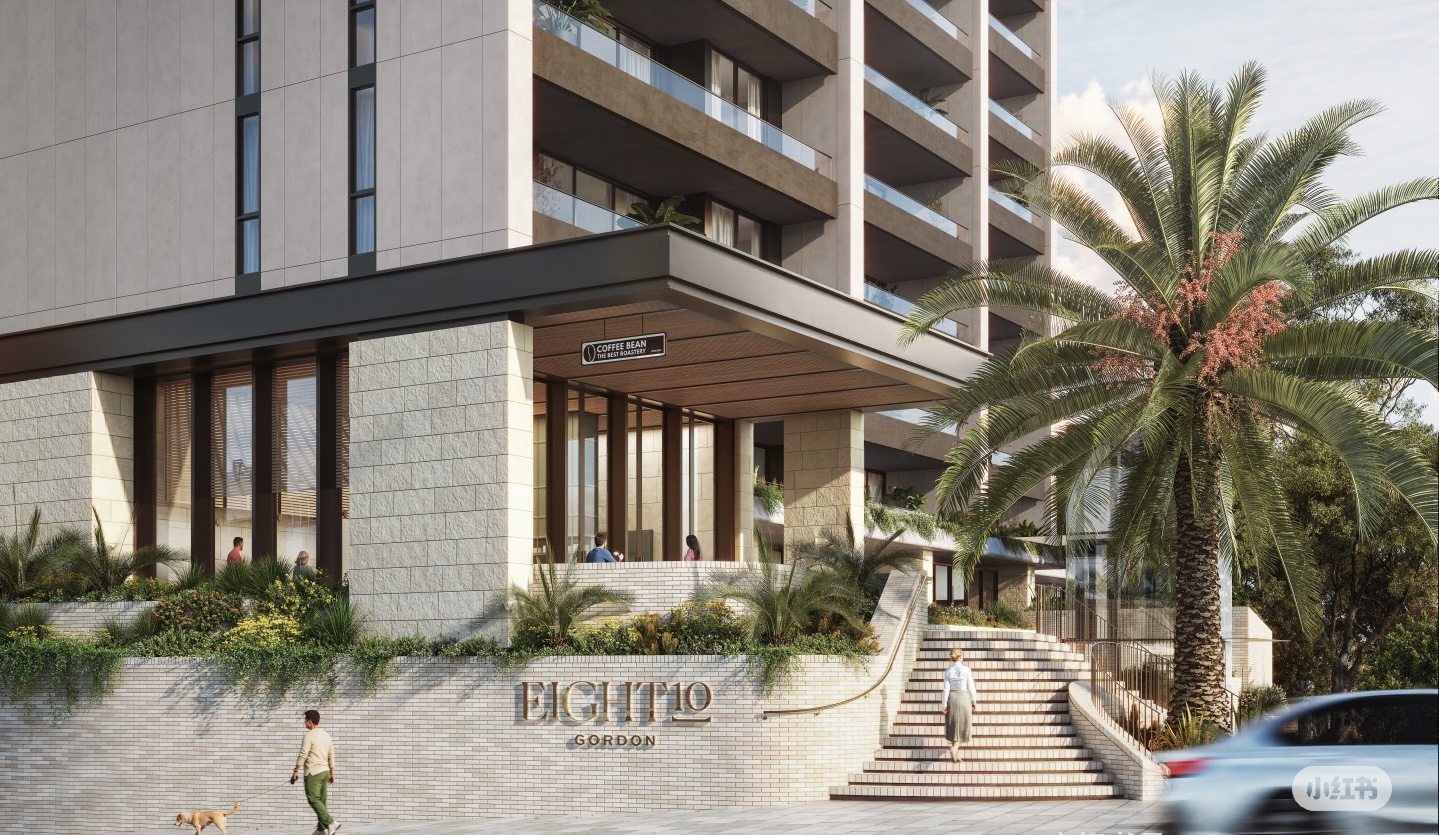
Eight10 Gordon
A boutique collection of thoughtfully designed residences moments from Gordon Station, village shopping and leading North Shore schools.
PrimeLine Invest
We don't just find properties. We help buyers build portfolios, secure smarter loans, and make confident decisions that lead to financial freedom — across Sydney's fastest-growing corridors.
Book a Buyer Consultation$150M+
Real Estate Assets Under Strategy
14 Days
Average Campaign Preparation Time
1-on-1
Dedicated Client Representation
100%
Client Satisfaction & Retention
Established apartments in St Leonards, off-plan developments in Gordon and Melrose Park, and house & land packages in Tallawong, Rouse Hill and Leppington.
Gordon, NSW — Off-Plan
A boutique collection of thoughtfully designed residences moments from Gordon Station, village shopping and leading North Shore schools.
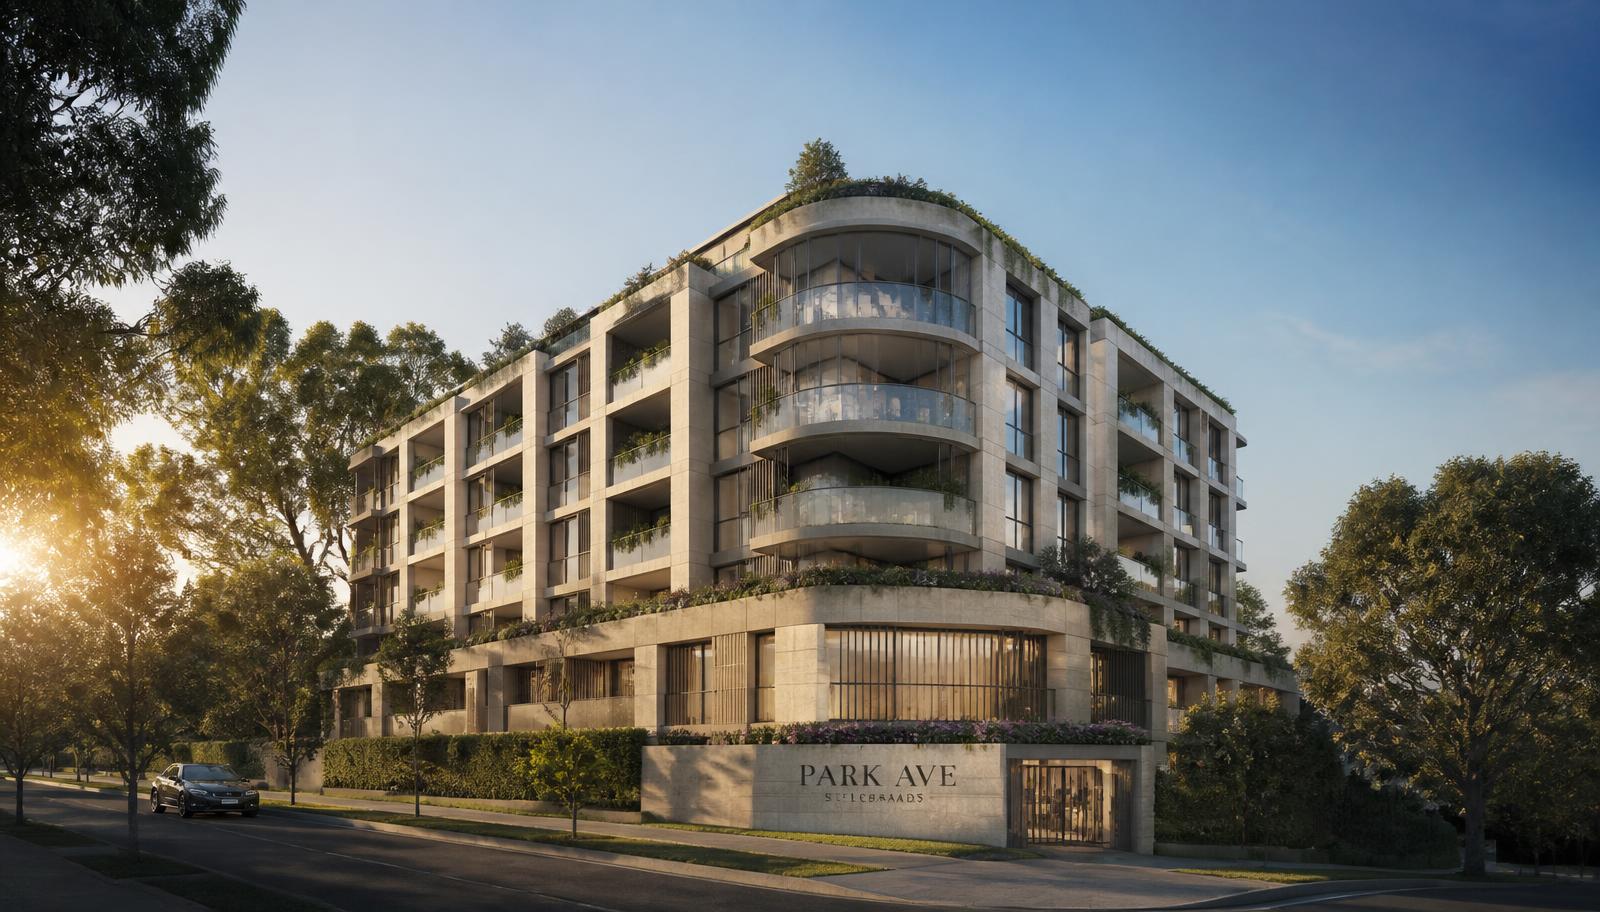
St Leonards, NSW — Established
A boutique established apartment residence in the heart of St Leonards — moments from the station, St Leonards Plaza and the lower north shore's thriving commercial and dining precinct. Ready for immediate entry.
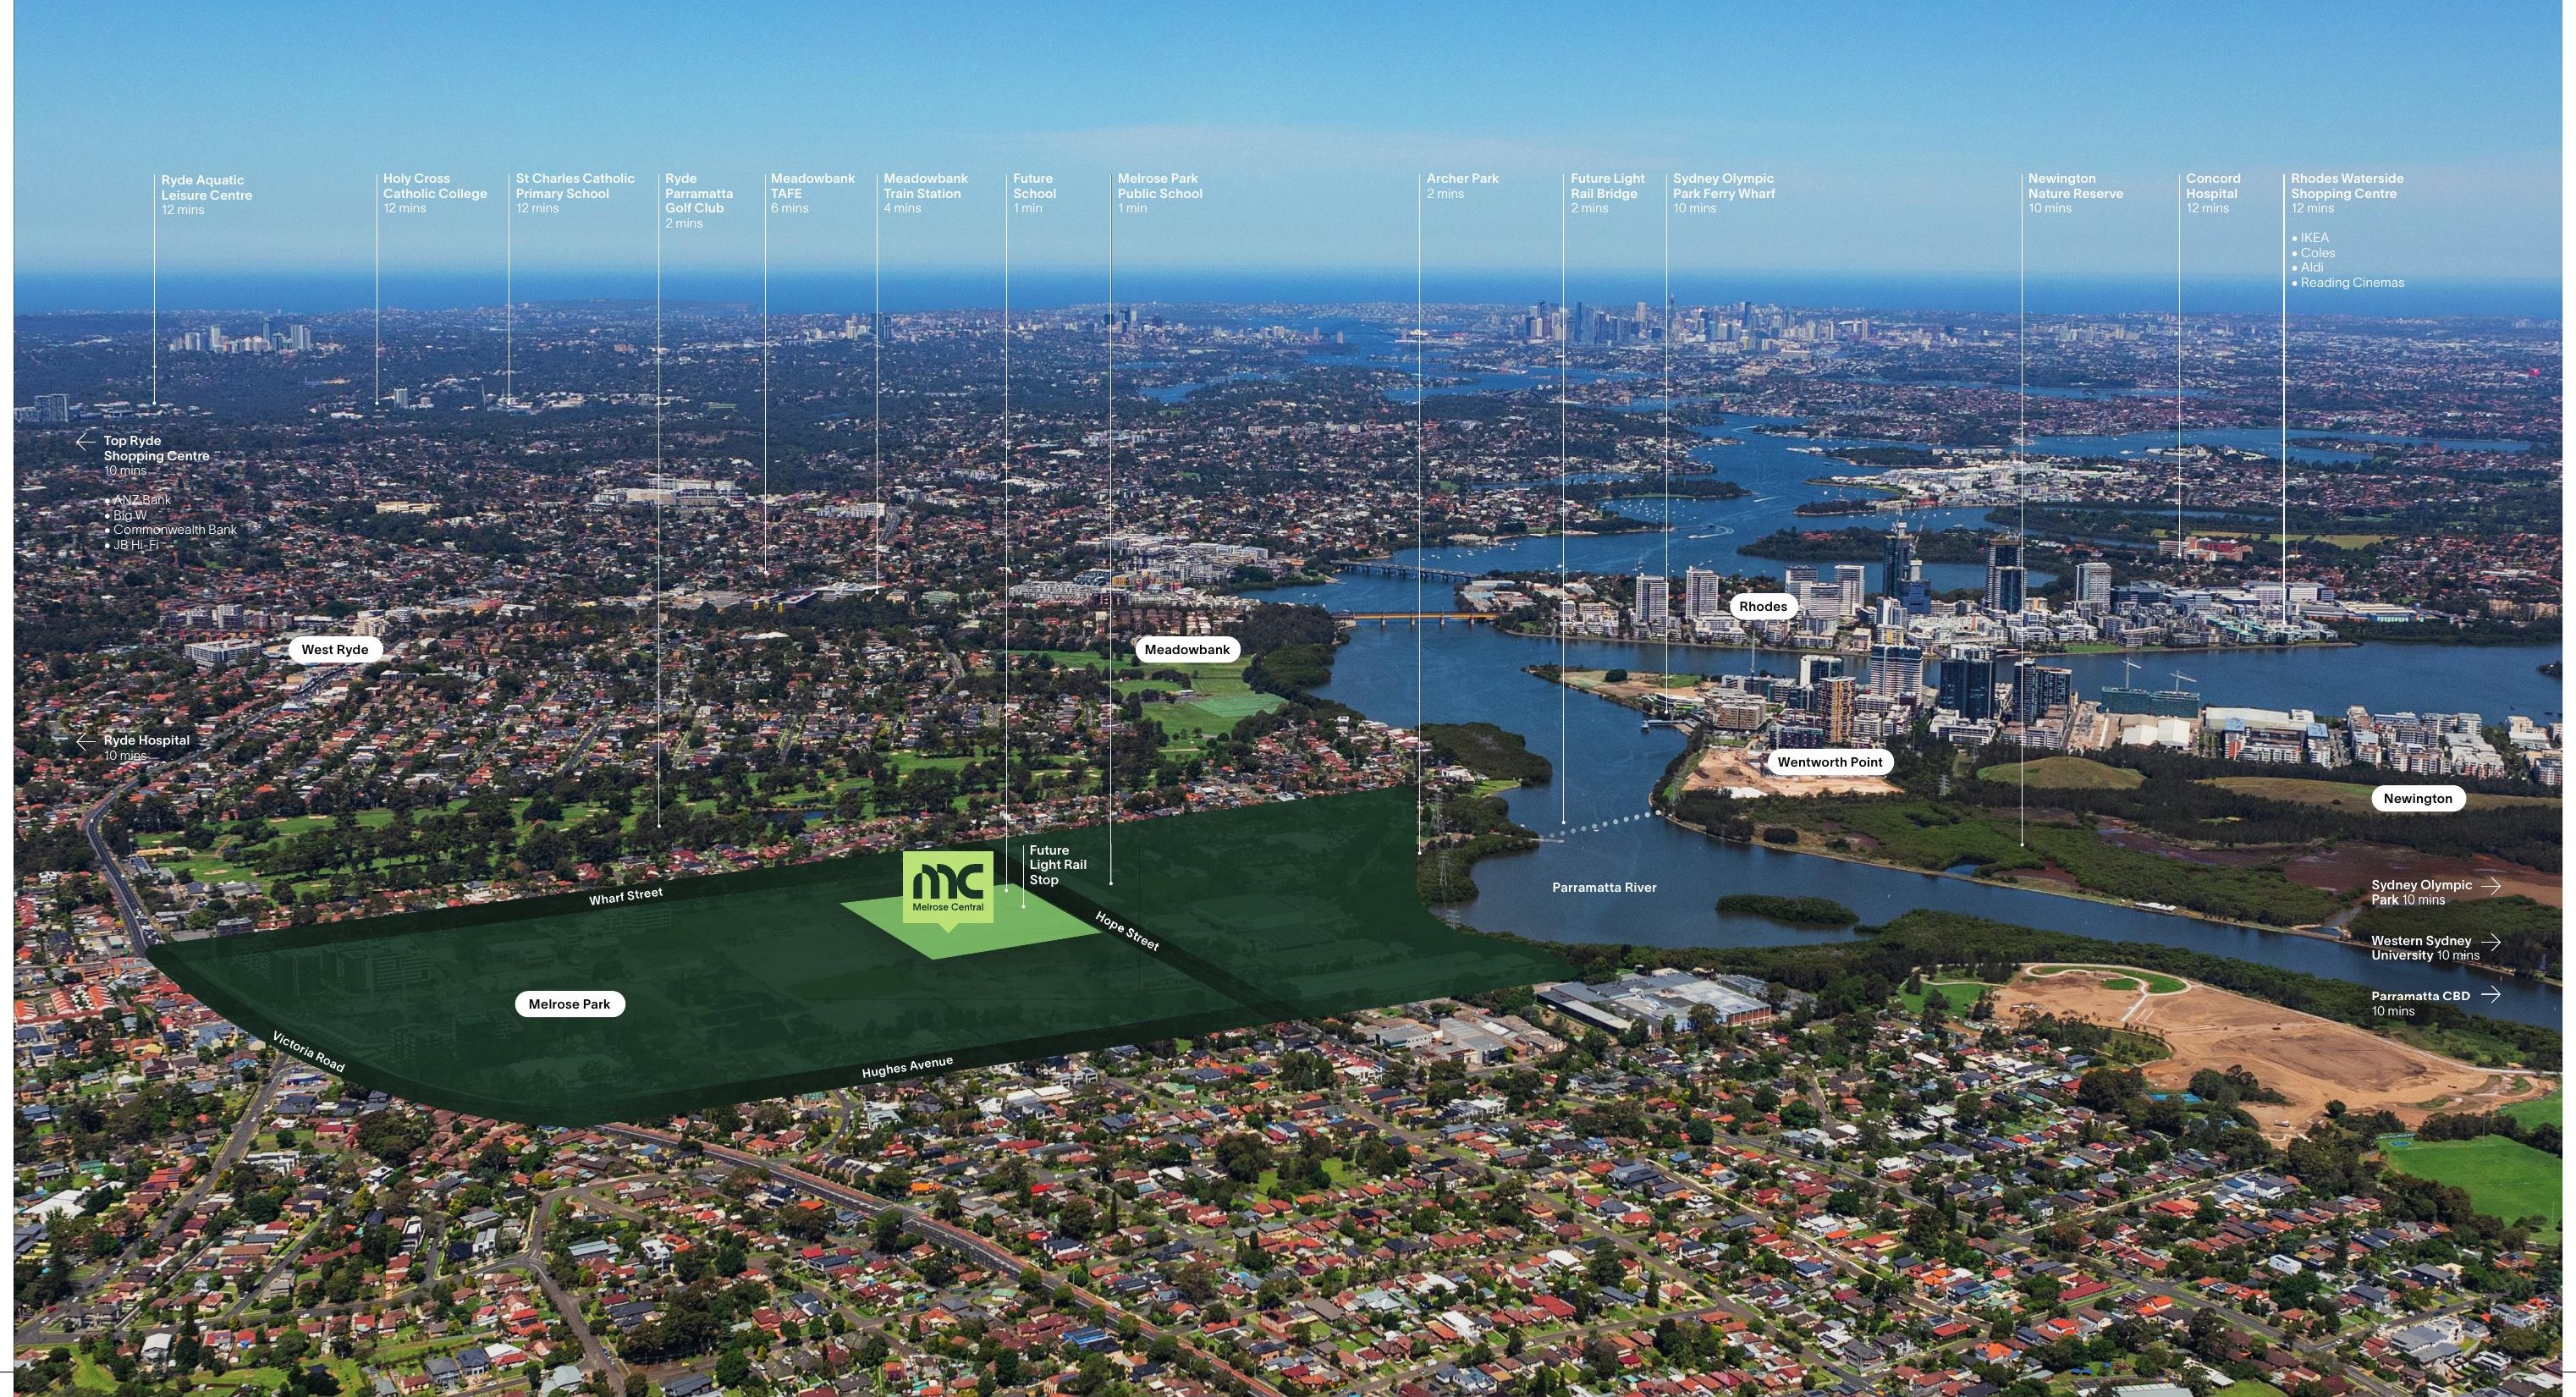
Melrose Park, NSW — Off-Plan
A riverfront precinct between Sydney's two largest CBDs, with a future light rail stop and 400 hectares of parkland at its doorstep.
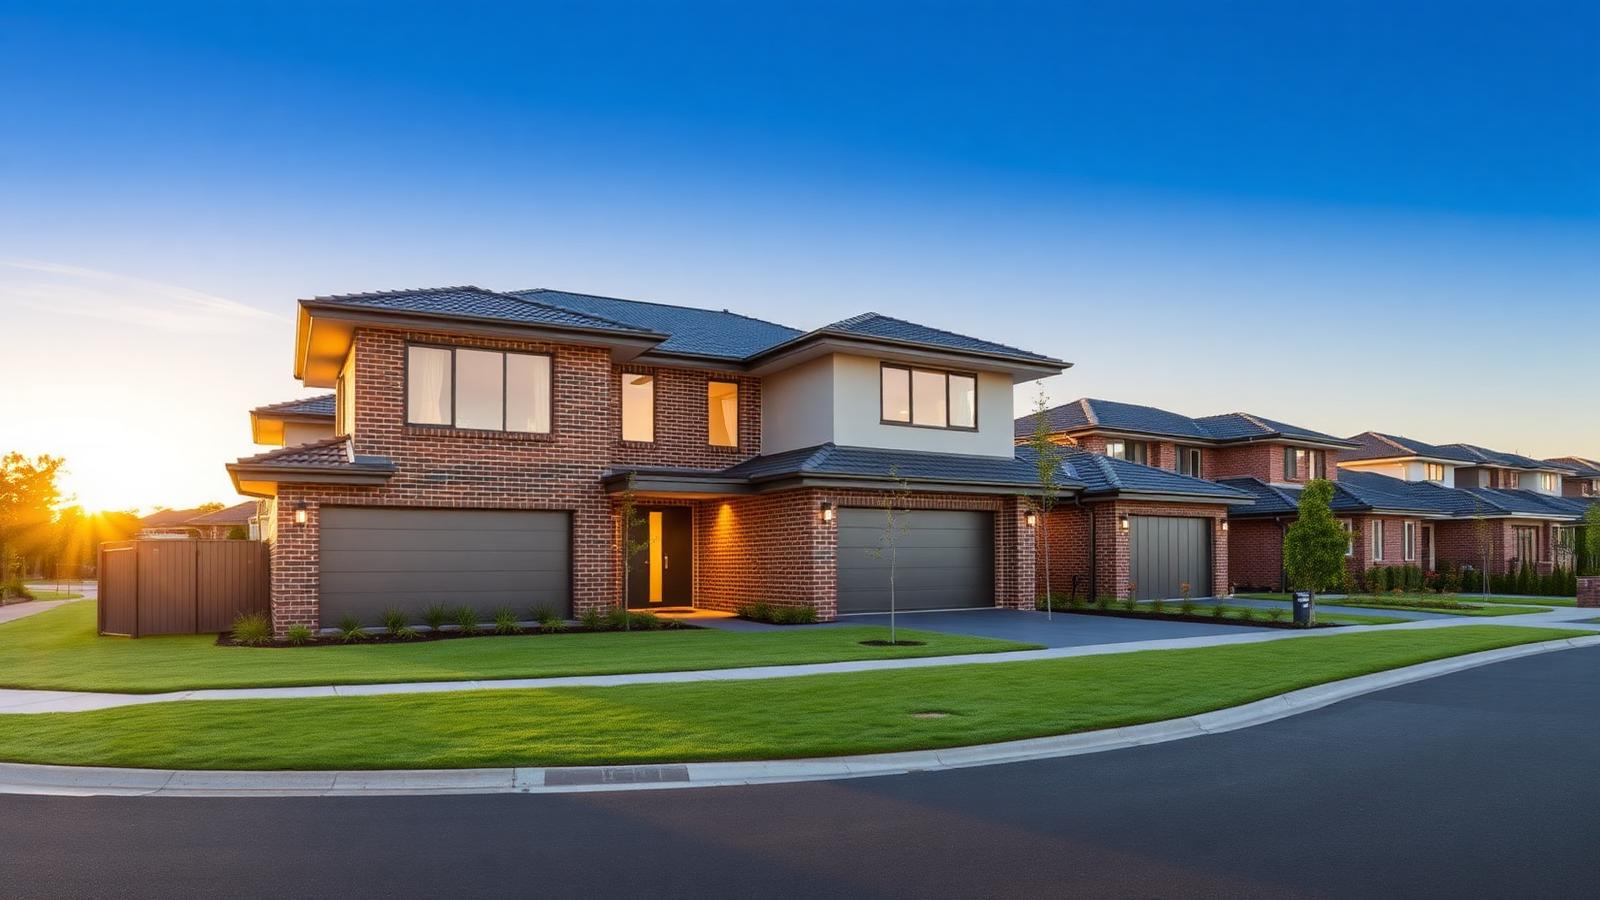
Tallawong, NSW — House & Land
Brand-new house and land packages moments from Tallawong Metro Station, in one of Sydney's fastest-growing northwest corridors.
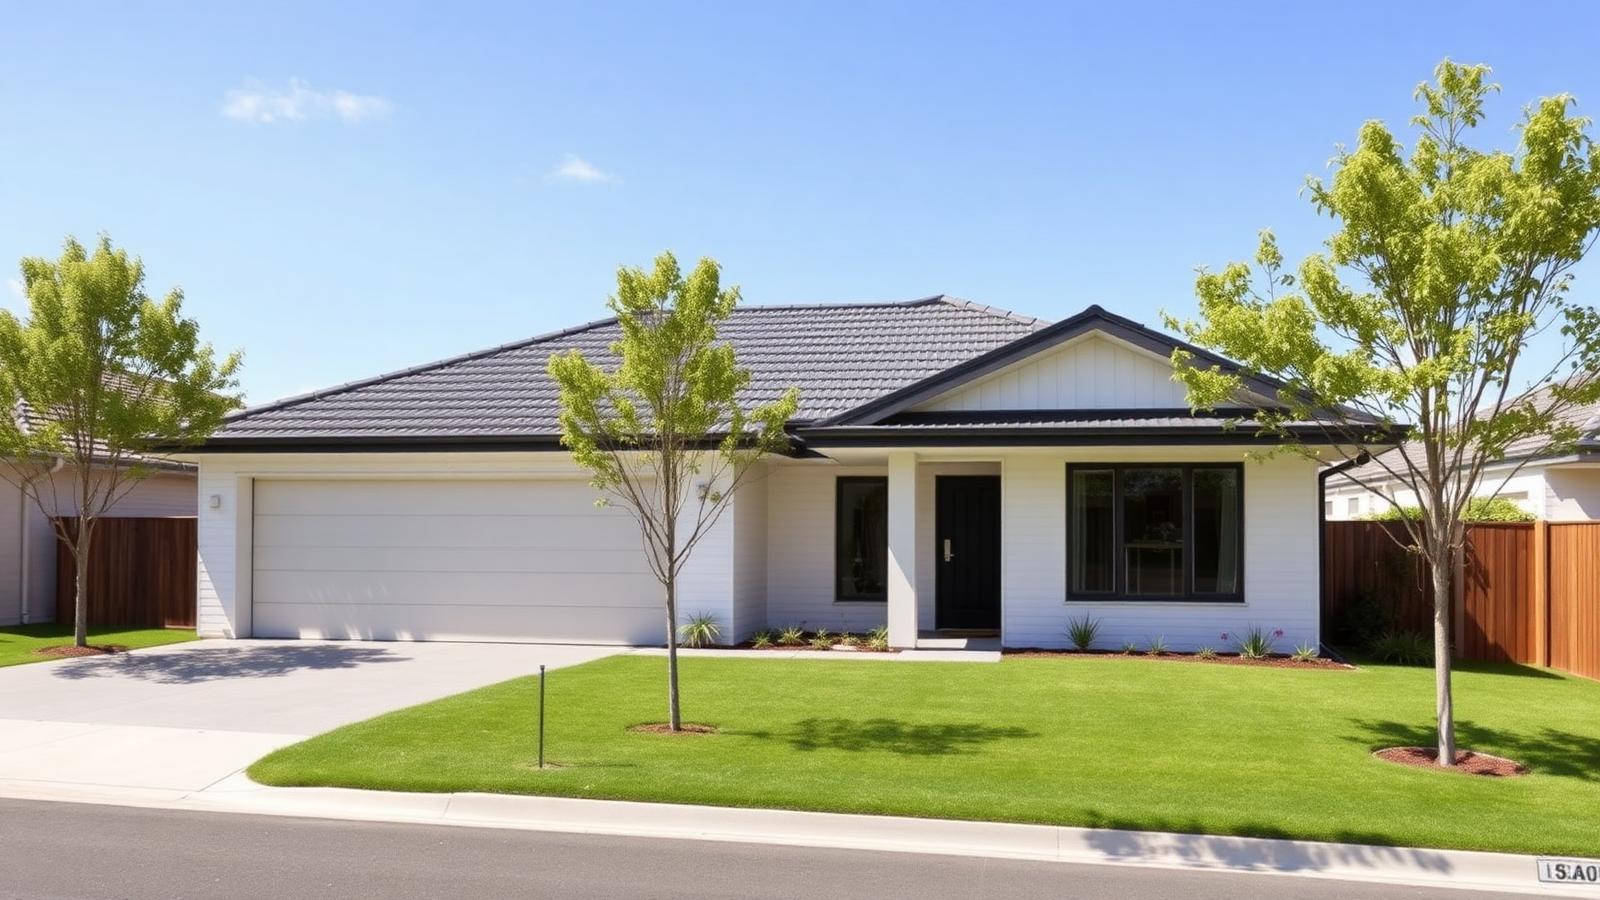
Rouse Hill, NSW — House & Land
Family-friendly house and land packages near Rouse Hill Town Centre, the Metro, parks and quality schools.
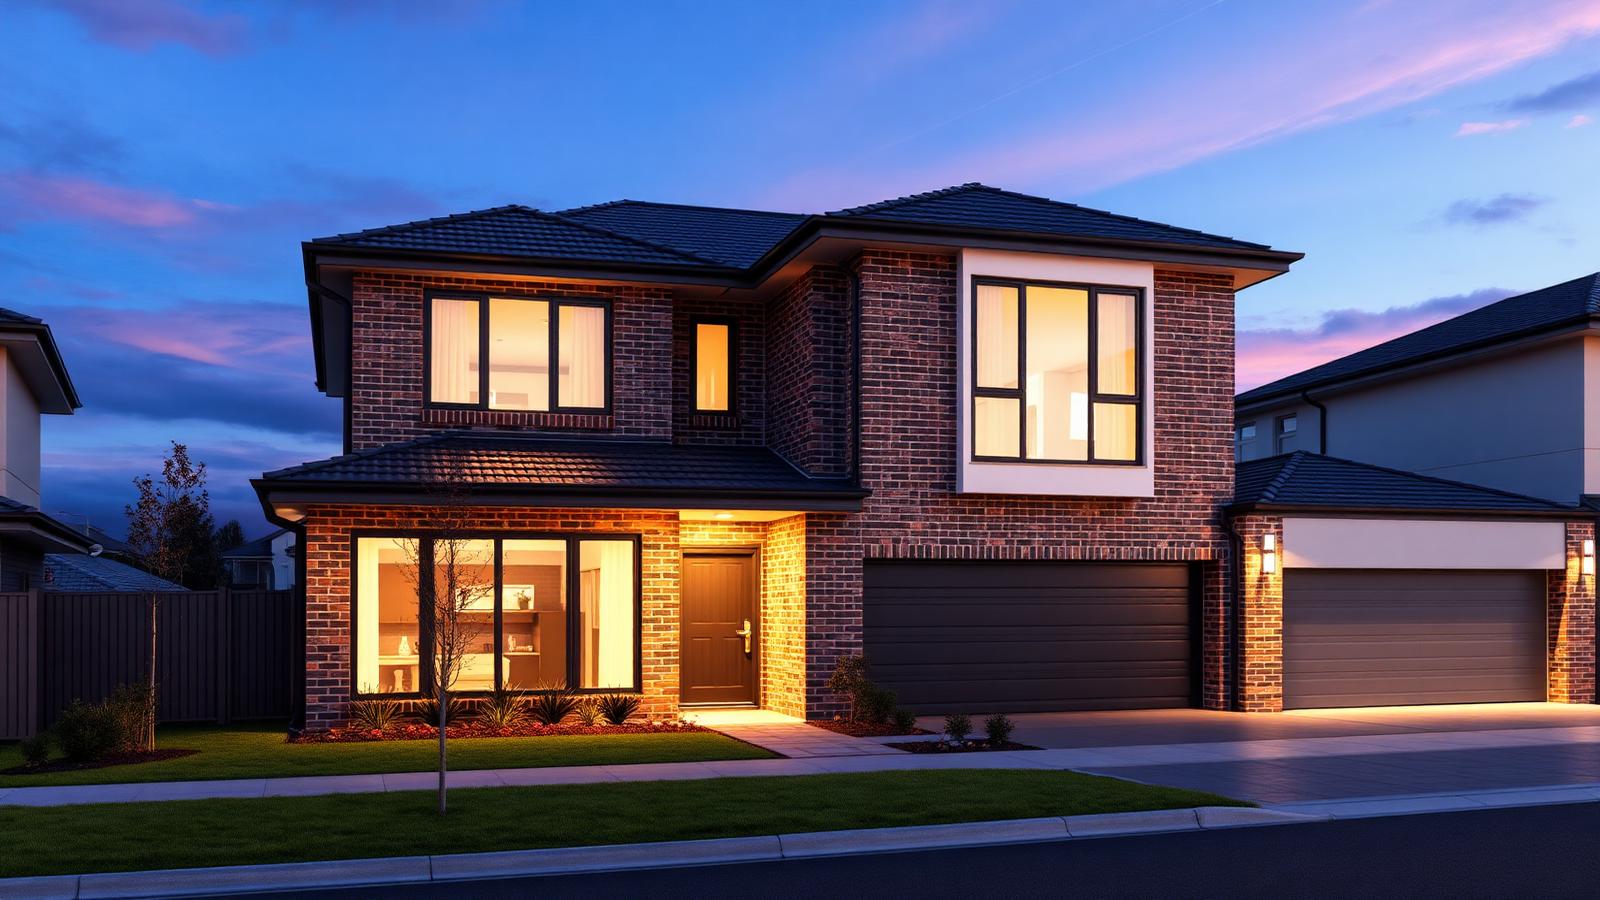
Leppington, NSW — House & Land
House and land packages in Sydney's Southwest Growth Area — near Leppington Station and the future Western Sydney Airport.
Sydney Market Education
Property markets move through periods of expansion, slowdown and recovery. The current outlook points to near-term softness followed by a gradual rebound, creating a window for prepared buyers to focus on quality, value and long-term fundamentals.
20-Year Perspective
Price index, June 2020 = 100. Forecast period begins after 2024.
Higher borrowing costs and softer confidence are expected to weigh on Sydney houses, while unit values are forecast to remain steadier.
−4.4% houses · 0.0% units
Population-led demand, low vacancy and a persistent shortage of new homes may support the market as short-term pressure eases.
Supply remains constrained
KPMG forecasts Sydney prices returning to growth, with affordability likely to keep the recovery measured rather than speculative.
+3.6% houses · +3.4% units
Long-term direction: Sydney values have risen materially across several cycles since 2006.
Current phase: KPMG expects 2026 weakness to be relatively short-lived.
Next phase: A measured recovery is forecast for 2027, supported by constrained supply.
20-Year Perspective
Annual GDP growth and the RBA cash rate, in per cent.
2008 – 2012
Economy and property moved together
The global financial crisis slowed growth and prices at the same time. Rate cuts stabilised both, and Sydney values recovered as the economy did.
2013 – 2021
Interest rates mattered more than growth
Economic growth was only moderate, yet Sydney prices surged. Falling interest rates and borrowing capacity drove the property cycle more than GDP.
2022 – 2027
Rates lead, property follows
Rapid rate rises cooled prices while the economy kept growing slowly. As rates ease, property typically turns before broader economic strength returns.
Are the two cycles aligned? Partly. Deep economic shocks pull property with them, but over the past twenty years Sydney prices have tracked interest rates and credit conditions far more closely than GDP growth. Property also turns with a lag, typically six to twelve months after rates move. For buyers, the practical signal is the direction of interest rates and borrowing capacity, not headline economic growth.
Sources: Australian Bureau of Statistics national accounts and Reserve Bank of Australia cash rate history. 2025 onwards are estimates and forecasts, shown for education only.
The Buyer's Window
History shows that property turns six to twelve months after interest rates begin falling. With the RBA easing and a recovery forecast for 2027, the next 12–18 months may offer the strongest negotiating position of the cycle — softer prices, motivated vendors, and improving borrowing capacity. Buyers who position now are ready to act before the broader market does.
What this means for you: A softer market can improve choice and negotiating conditions, but timing alone is not a strategy. Property quality, location, finance capacity and holding horizon remain essential. We help you weigh each of these so your next move is deliberate, not reactive. Forecasts are indicative, not guaranteed.
Source: KPMG Australia, Residential Property Market Outlook, August 2026. Sydney forecasts shown are year-on-year estimates to December 2026 and December 2027. The 2025 index values are derived from KPMG's published 2026 forecast rates for continuity in the chart.
From Our Investors
“PrimeLine didn't just find us a property — they helped us build a strategy. We finally feel in control of our financial future.”
Sarah & James M.
First-time investors
“They knew exactly which suburbs suited our budget and goals. The personal service and loan guidance made all the difference.”
David Chen
Portfolio buyer